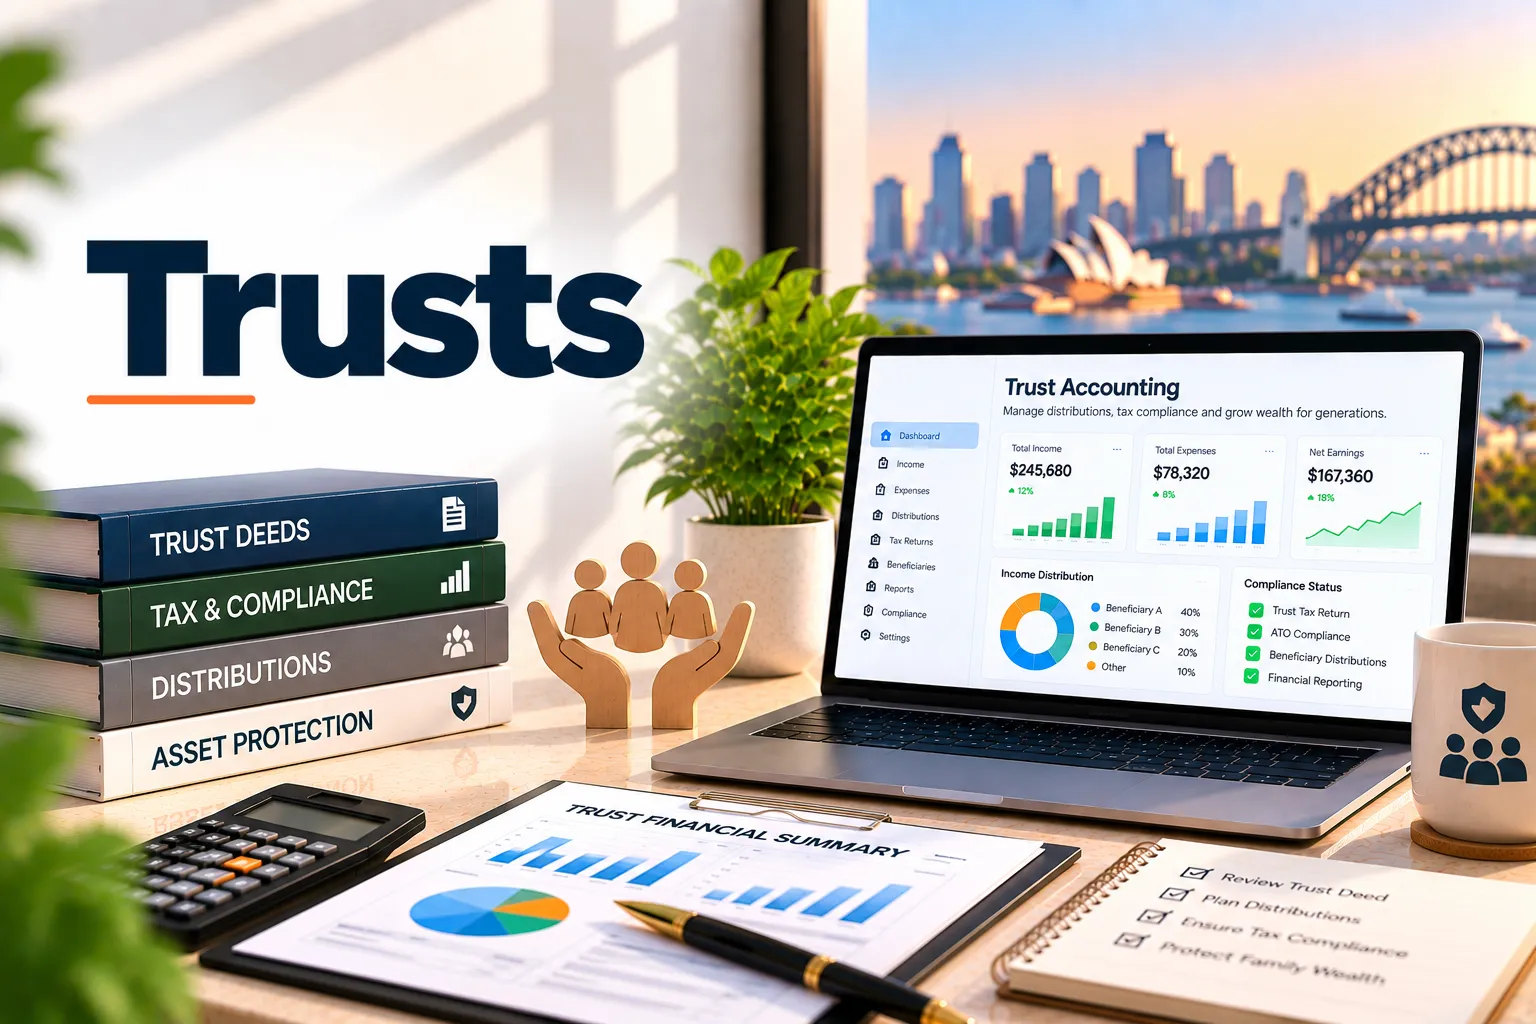
Trust structures can be useful for holding assets, operating a business or managing interests for beneficiaries, but they also come with specific legal, accounting and tax responsibilities. All In One Accounting Solutions provides trust structure advice, accounting, tax and ongoing compliance support for individuals, families, investors and businesses in Melbourne and across Australia.
Whether you are considering a trust for the first time or already operate through one, we can help you understand how the structure works, how its accounting and tax obligations should be managed, and when the structure may need to be reviewed.
A trust is a legal arrangement in which a trustee holds or manages property or assets for the benefit of other people or entities, known as beneficiaries. A trustee may be an individual or a company, and the trustee is responsible for the operation of the trust.
Trusts are different from companies. A company is a separate legal entity, whereas a trust is a legal relationship governed by its trust deed and applicable law. The trustee is the entity that undertakes the responsibilities associated with operating the trust.
The right structure depends on what you are trying to achieve, the assets involved, the people or entities who will benefit, tax considerations, administration requirements and your longer-term plans. A trust should not be established simply because it is commonly used. Its suitability needs to be considered in the context of your circumstances.
A discretionary trust generally gives the trustee discretion over distributions among eligible beneficiaries, subject to the trust deed and applicable tax rules. Family trusts are commonly used where a family group is involved, but the term 'family trust' also has a specific tax meaning in Australian tax law. Establishing a family trust and making a family trust election are not the same thing.
A unit trust generally gives beneficiaries interests represented by units. It can be suitable where ownership or entitlement needs to be linked to defined unit holdings. The deed, unit ownership and distribution arrangements need to be considered carefully.
A bare trust is generally used where a trustee holds an asset for a beneficiary who is entitled to the asset and its benefits. Bare trusts can arise in specific investment, property or transaction arrangements, so the intended purpose should be clearly established before the structure is used.
Preparation and review of trust accounting records.
Trust income and expense classification.
Trust tax return preparation and tax compliance support.
Beneficiary distribution calculations and supporting records.
Review of trust distributions and beneficiary reporting considerations.
Capital gains and other relevant tax components within trust tax reporting.
BAS, GST and activity statement support where applicable.
Year-end accounts and financial reporting.
Trust compliance and record-keeping support.
Accounting support for property, investment and business trusts.
Coordination with legal advisers where deed or legal changes require legal input.
A trust separates the legal responsibility for managing trust property from the people or entities who may benefit from it. The trustee manages the trust according to the trust deed and applicable legal and tax requirements, while beneficiaries may have rights to trust income or capital depending on the type of trust and the terms of the deed.
Common trust arrangements include discretionary or family trusts, unit trusts and bare trusts. These structures can have very different purposes, rights and tax outcomes, so the terms of the trust deed and the intended use of the structure are important.
A trust may be used in connection with a trading business, investment assets or property. However, the fact that a trust can be used for these purposes does not mean that it will automatically be the most suitable structure.
The main elements of a trust include:
A unit trust generally gives beneficiaries interests represented by units. It can be suitable where ownership or entitlement needs to be linked to defined unit holdings. The deed, unit ownership and distribution arrangements need to be considered carefully.
See Unit Trust Setup.
A bare trust is generally used where a trustee holds an asset for a beneficiary who is entitled to the asset and its benefits. Bare trusts can arise in specific investment, property or transaction arrangements, so the intended purpose should be clearly established before the structure is used.
See Bare Trust Setup.
A trust may be considered where there is a genuine need to hold assets for beneficiaries, operate a business through a particular ownership arrangement, manage investment interests or support longer-term ownership and succession objectives.
The decision should consider more than tax. Setup costs, ongoing administration, trustee responsibilities, asset ownership, financing, distribution rules, record keeping and future restructuring can all affect whether a trust is appropriate.
For business owners, the choice may also need to be considered alongside a company, sole trader or partnership structure. A structure that works at one stage of a business may not remain suitable as ownership, risk, assets or commercial objectives change. See Business Structures.
Trust distributions need to be considered in the context of the trust deed, the income of the trust, beneficiary entitlements and applicable tax rules. The way trust income is allocated for tax purposes can depend on the nature of the income, the terms of the deed and the actions taken by the trustee.
This is an area where accurate records and timely decisions matter. Distribution documentation should align with the trust governing documents and the applicable tax requirements. Beneficiary reporting also needs to be considered when preparing individual or entity tax returns.
We can assist with the accounting and tax side of trust distributions and work with your legal adviser where legal interpretation of the deed is required.
The trustee has significant responsibilities because the trustee operates and administers the trust. These responsibilities can include managing trust assets, maintaining records, complying with the trust deed, making distributions in accordance with the deed and meeting relevant tax and reporting obligations.
Where a company acts as trustee, the company has its own corporate obligations in addition to its role as trustee. This can create additional administration and compliance requirements that should be considered when establishing or reviewing the structure.
If you are considering a trust, the structure should be designed around its intended purpose before assets or business activities are transferred into it. We can help you assess the accounting, tax and commercial considerations and identify the information your legal adviser may need when preparing or reviewing the trust documentation.
A trust should not be treated as a set-and-forget structure. Changes in business activities, asset ownership, beneficiaries, distributions, borrowing arrangements or long-term plans may create a reason to review how the trust is being used.
A review can consider whether the existing structure continues to support your objectives, whether accounting and tax records are being maintained correctly, and whether professional advice is needed before making changes.
Where a legal change to the trust deed or structure is required, we can work alongside your solicitor or other qualified legal adviser. Accounting and tax advice does not replace legal advice on the interpretation or amendment of trust documents.
A trust is one of several common Australian business structures. Sole traders generally operate a business personally, partnerships involve two or more partners, companies operate as separate legal entities, and trusts are operated by trustees for beneficiaries.
The right choice depends on ownership, liability, tax, administration, control, costs and future plans. Changing structure later can also have tax and legal consequences, so it is worth considering the longer-term position before establishing or transferring assets into a structure. See Company, Sole Traders and Partnerships.
Trusts can have ongoing tax, accounting and administrative obligations. Depending on the trust and its activities, these may include maintaining financial records, preparing and lodging a trust tax return, managing GST or BAS obligations, keeping beneficiary records and meeting requirements associated with distributions.
The trustee remains responsible for the trust obligations even when an accountant or other professional is engaged to assist with compliance. Good records and a clear annual compliance process can help reduce the risk of missed obligations.
We start by understanding the purpose of the proposed or existing trust, its beneficiaries and commercial objectives. We then explain the relevant accounting and tax considerations in clear language and support the ongoing compliance requirements:
We discuss the purpose of the proposed trust, including assets, business or investment interests.
We consider the intended beneficiaries and the type of trust that may suit the objectives.
We review the proposed trustee arrangement, including individual or corporate trustee.
We consider accounting, tax, registration and ongoing administration requirements.
We coordinate with your legal adviser on the trust deed and legal documentation.
We establish accounting records and review the structure as circumstances change.
Trust structure advice Melbourne u2014 accounting, tax and business advisory support for new and established trusts.
A trust is a legal arrangement in which a trustee holds or manages property or assets for the benefit of beneficiaries. The trustee is responsible for operating the trust in accordance with the trust deed and applicable requirements.
A trust is not a separate legal entity in the same way as a company. The trustee is responsible for the trust and may be an individual or a company.
A trustee is the person or company responsible for managing the trust, its assets and its administration in accordance with the trust deed and applicable obligations.
A beneficiary is a person or entity that may benefit from the trust under the terms of the trust deed. The nature of the entitlement depends on the type of trust and the deed.
A trust deed is the document that establishes and governs the trust. It sets out important rules concerning the trustee, beneficiaries, powers and administration of the trust.
They can overlap in common usage, but the terms should not be treated as identical for every purpose. A family trust can also have a specific meaning for Australian tax purposes, so the relevant tax elections and definitions need to be considered separately.
Yes. A business can be operated through a trust, with the trustee responsible for the business operations. Whether this is suitable depends on the circumstances, structure and objectives of the business.
Many trusts have tax reporting obligations, including lodging a trust tax return. The exact requirements depend on the trust and its circumstances.
Changes can be possible, but they may have legal, tax and administrative consequences. Any proposed change should be reviewed before it is implemented, particularly where the trust deed or ownership of assets is affected.
We can discuss the accounting, tax and commercial considerations relevant to your circumstances and help you compare the trust structure with other options. Legal advice should be obtained where the proposed arrangement involves legal structuring or trust deed matters.
Considering a trust structure, reviewing an existing trust or looking for ongoing trust accounting and tax support? Speak to an expert to discuss your requirements.
Copyright © 2026 All In One Accounting Solutions. All rights reserved.
Speak with one of our senior Melbourne accounting & tax specialists.
Thank you. Your call has been successfully scheduled with our expert team.
A calendar invitation and confirmation email have been sent to your inbox.